My Husband Asked Me to Sign Away Our Family Home to Save His Business. Then I Found Out Who Was Really Getting the Money.
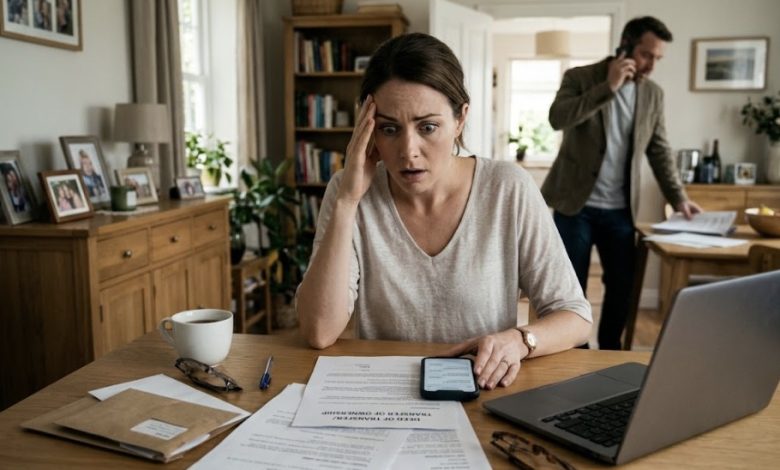
My husband wanted me to put our paid-off house up as collateral for an $180,000 business loan. He said the company couldn’t survive another winter without it. I was ready to sign until I found an $84,000 invoice from a consulting firm I’d never heard of. The firm’s address was a mailbox store twelve miles away. When I asked my husband about it, he told me to stop interfering. That was the first time I realized our house might not be the thing he was trying to save.
I had always been the person who kept things organized.
At home, that meant remembering the furnace filters, renewing the car insurance, and knowing which kitchen drawer contained the batteries.
At my husband’s company, it meant making sure suppliers got paid and customers received their invoices.
Nothing glamorous.
But somebody had to do it.
My name is Natalie Brooks. I’m fifty-one, and I live outside Grand Rapids, Michigan.
My husband, Owen, started his commercial flooring business eleven years ago with one used van, three employees, and a borrowed warehouse.
For the first four years, I handled his bookkeeping after finishing my regular job at a dental office.
Eventually, the company grew enough that he hired an accountant.
I went back to being his wife instead of his unpaid office assistant.
At least, that’s what I thought.
Owen had always been ambitious.
His business partner, Curtis Hale, was the opposite. Quiet, careful, and usually the first person to suggest waiting before spending money.
Curtis owned forty percent of the company.
Owen owned sixty.
They balanced each other, or so everyone said.
Then business slowed.
Two large construction projects were postponed, and several customers started paying late.
Owen became restless.
He stopped sleeping properly.
He would sit at our kitchen table with his laptop open long after midnight.
I started leaving a clean mug beside the coffee maker because he kept forgetting where he’d put the previous one.
One Sunday in September, he told me we needed a loan.
“Just until spring,” he said.
“How much?”
“One hundred eighty thousand.”
I almost dropped the dish towel.
“Owen, that’s not a little bridge loan.”
“I know.”
“What’s the collateral?”
He looked toward the living room.
I understood before he answered.
Our house.
The same house we’d spent twenty-three years paying off.
The house where our daughter, Madison, had taken her first steps.
The house where I’d sat on the basement stairs crying after my mother died because I didn’t want Madison to hear me.
“We have plenty of equity,” Owen said.
“That’s not the point.”
“I would never risk our home unnecessarily.”
I believed he meant it.
For another week, anyway.
The invoice appeared on a Wednesday.
Owen had asked me to retrieve an insurance certificate from the office computer because his administrative assistant was away.
While searching the shared company folder, I noticed an invoice labeled “Strategic Advisory Services.”
$84,000.
The vendor was Westbridge Operations Consulting.
I’d never heard of it.
The description said the payment covered business restructuring and operational planning.
It seemed strange that a company struggling to meet payroll would spend that much on advice.
I printed the invoice.
At dinner, I asked Owen what Westbridge did.
His fork stopped moving.
“Where did you see that?”
“In the office folder.”
“Why were you looking at invoices?”
“I was finding the insurance certificate you asked for.”
He put down his fork.
“That’s Curtis’s department.”
“Then what are they advising you about?”
“Natalie, please. I have enough problems without you examining every expense.”
He’d never spoken to me quite like that.
I didn’t answer.
I just picked up my plate and carried it to the sink.
The next morning, I looked up the consulting firm’s address.
It belonged to a commercial mailbox store.
That wasn’t proof of anything. Small businesses use mailing addresses all the time.
But it bothered me.
Especially when I noticed the invoice listed payment instructions for a bank account that wasn’t familiar from the old supplier records I still had.
I called Curtis.
He sounded tired.
“Westbridge?” he repeated.
“Yes.”
A pause.
“Where did you hear that name?”
“Owen’s office.”
Another pause.
“Natalie, you need to ask Owen.”
“I already did.”
“Then I’m sorry.”
He ended the call sooner than usual.
That afternoon, I drove to the office.
Owen was out visiting a job site.
His accountant, Denise, was preparing quarterly reports.
I’d known Denise for six years.
She was a serious woman who wore reading glasses on a chain and always kept peppermint candies in a little glass bowl.
I asked whether she had five minutes.
She looked at the invoice.
Her expression changed.
“Have you signed the loan documents?”
“No. Friday.”
“Have you reviewed the company’s current financial statements?”
“Owen said everything was being prepared.”
Denise placed the paper face down.
“I can’t discuss confidential company information without authorization.”
“I understand.”
She hesitated.
“But if you’re personally guaranteeing a loan with your home, you should have independent legal advice.”
“Is something wrong?”
“I can’t answer that.”
Her hands were perfectly still.
Mine weren’t.
I thanked her and left.
Outside, I sat in my car for nearly twenty minutes.
Then I called a lawyer whose office had helped settle my mother’s estate.
He couldn’t see me until Thursday afternoon.
I took the appointment.
That night, Owen asked whether I had found our property documents.
“Yes,” I said.
“Good. Friday should be straightforward.”
I watched him spread mustard on a sandwich.
He was humming.
For the first time in weeks, he seemed relaxed.
And that frightened me more than his anger had.
On Thursday morning, Curtis’s wife, Ellen, called.
We weren’t particularly close, but we’d known each other for years.
Her voice sounded strained.
“Natalie, did Owen tell you Curtis is leaving the business?”
I sat down.
“No.”
“He’s been trying to get out for months.”
“Why?”
She exhaled.
“Because Owen wants the company to pay Westbridge for a restructuring project Curtis doesn’t believe is necessary.”
I looked at the invoice lying beside my laptop.
“Who owns Westbridge?”
Ellen hesitated.
“That’s what Curtis has been trying to find out.”
Then she told me something else.
Curtis had refused to approve the payment.
And Owen had been looking for financing that would give him enough money to proceed without Curtis’s support.
I stared at the date on the invoice.
It had been issued two weeks before Owen asked me to put our house on the line.
“Does Curtis know about the loan?” I asked.
“He knows Owen has been looking for financing. He doesn’t know what Owen has promised the bank.”
After we hung up, I called the lawyer’s office and asked whether I could email the invoice before our appointment.
His name was Peter Lawson.
He called me back an hour later.
“Natalie, don’t sign anything until we’ve reviewed the actual loan documents.”
“Do you think it’s fraud?”
“I don’t have enough information to say that. But you’re being asked to accept a very serious financial risk.”
At our appointment, Peter explained that a personal guarantee could leave me responsible for the debt even if the company failed.
The mortgage documents could also place our home at risk.
He asked why the company needed exactly $180,000.
I couldn’t answer.
He asked whether I knew what portion would go toward payroll, materials, or existing debt.
Again, I couldn’t answer.
“Then you don’t have enough information to make this decision,” he said.
I felt embarrassed.
Not because I was foolish.
Because I’d spent eleven years helping that company survive, and somehow I’d become the person who knew the least about its finances.
Peter advised me to request the company’s financial statements, the proposed loan agreement, and an explanation of the Westbridge invoice.
That evening, I told Owen I wouldn’t sign on Friday.
He stared at me.
“What?”
“Not without seeing the paperwork.”
His face reddened.
“You talked to a lawyer?”
“Yes.”
“Behind my back?”
I almost laughed.
“You’re asking me to risk our house, Owen.”
“After everything I’ve done for this family?”
“Everything we’ve done.”
He turned away.
Then he said something I couldn’t forget.
“If this falls apart, don’t blame me.”
The following Monday, Curtis requested a formal meeting with Owen and the company’s accountant to review the proposed expenditure.
As a shareholder, Curtis had been demanding access to supporting records for weeks.
Owen finally agreed.
The meeting wasn’t the dramatic confrontation I’d imagined.
There was no shouting at first.
Just documents.
The consulting agreement identified Westbridge as a recently formed company managed by a woman named Melissa Grant.
Curtis recognized the name.
She had previously worked with Owen on a commercial property development project.
Owen admitted that Melissa had approached him with a proposal to establish a separate flooring distribution business.
Westbridge’s $84,000 fee was supposed to cover planning, supplier negotiations, and startup services.
But the proposed distribution company would be owned by Owen and Melissa personally.
Not by the flooring business that was supposed to pay Westbridge.
Curtis leaned forward.
“You’re using our company to fund a business I don’t own?”
Owen insisted the distribution operation would eventually benefit everyone through cheaper materials.
Curtis asked why it hadn’t been disclosed and approved before the invoice was issued.
Owen didn’t have a convincing answer.
The invoice hadn’t been paid, and the meeting didn’t establish whether anything illegal had occurred.
But the documents made one thing painfully clear.
Owen had wanted our home to help finance a plan whose risks and potential rewards he hadn’t fully explained to either his partner or me.
The loan application was withdrawn.
Curtis hired his own attorney.
Within two months, the partners negotiated a separation. Owen sold his interest under an agreement that required payments over time, rather than the immediate cash he’d hoped for.
The business survived under Curtis’s management.
Our marriage didn’t.
I moved into the small guest bedroom while Owen searched for an apartment.
We tried counseling twice.
Both times, he insisted he’d only been trying to build something better for our future.
Maybe he believed that.
But when I asked why he hadn’t told me the truth, he kept saying I wouldn’t have understood.
One evening, I found him packing his old desk calendar.
There was a photograph tucked inside.
Madison, age seven, sitting on his shoulders at a county fair.
He held it for a long time.
“I really thought I could make it work,” he whispered.
I believed him.
That was the saddest part.
I believed he had wanted success.
I just no longer believed he knew the difference between building a future together and making decisions that everybody else would have to survive.
Six months later, we were living separately and working through the divorce.
I kept the house under our negotiated property settlement, with other assets and obligations divided between us.
It wasn’t a victory.
I still found his coffee mug behind the garage paint cans.
I still reached for my phone sometimes when something funny happened.
But on a rainy Saturday in April, Madison came home and found me sitting at the kitchen table, reviewing the budget for the little bookkeeping service I’d decided to start.
She pulled out a chair.
“Mom, are you scared?”
“Terrified.”
She smiled.
“You’re doing it anyway?”
I looked around the kitchen.
At the scratched countertop.
At the window that still stuck whenever the weather turned humid.
At the house I had almost put at risk because I was afraid of disappointing my husband.
“Yeah,” I told her. “I think I am.”
And for the first time in a very long while, the future felt like something I was allowed to have a say in.