My Husband Offered Our Home to His Father’s Lender
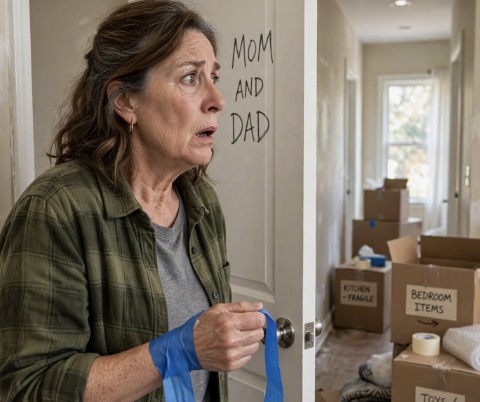
The blue painter’s tape comes off the guest-room door in one long strip, taking a little white paint with it. I stick it to my wrist and keep staring at the words my husband has written underneath: MOM AND DAD.
We haven’t even unpacked the kitchen, and Grant is already assigning bedrooms. His parents, Walter and Denise, are apparently coming to live with us, along with his sister, Marcy. Nobody has asked me. Grant tells me over leftover meatloaf from the grocery store that their moving truck arrives Saturday. He says it like he’s reminding me about a dentist appointment. I spent eleven years building a medical billing business, and the money from selling it bought this house. Grant knows that. He’s also known for months that I want the downstairs bedroom for my mother, who can’t manage stairs comfortably anymore.
I tell him his family cannot just move in. Not because I dislike them, but because we have never discussed supporting three additional adults. Walter has a history of borrowing money and avoiding uncomfortable questions about repayment. Denise excuses everything he does. Marcy has been staying with friends since her separation. I even offered to help find her an apartment last spring. Grant refused, saying his family handles its own problems. Apparently that means I pay for them. He don’t seem to notice the difference.
Grant puts down his fork. “My name doesn’t have to be on the deed for this to be my home.” I agree it’s his home, but that doesn’t mean he can invite permanent residents without a conversation. That’s when he tells me Walter has already changed his mailing address. Worse, Grant has given his father permission to use our address for business correspondence. I ask what business. He folds his napkin into a little square and won’t answer.
The next morning, Grant drives to the airport to collect everyone. I find a cream-colored folder behind the printer while looking for our internet installation receipt. Inside is a copy of a letter bearing Grant’s signature, addressed to someone at Brookfield Commercial Lending. Across the top, in bold type, are the words PROPERTY SUPPORT CONFIRMATION. I call my attorney, Lorna Bell, and read her the first paragraph. She interrupts before I finish. “Miriam, don’t sign anything else. There’s something in that document you need to understand.”
Lorna asks me to photograph the signature page. Beneath Grant’s name is a statement identifying him as an authorized representative of the property’s owner. The letter claims our house will serve as additional financial reassurance for Walter’s business loan.
Then Lorna notices the attached ownership declaration, supposedly signed by me…
The signature looks almost right.
That’s what bothers me most. Whoever wrote my name gets the first letter exactly the way I do, with the tall loop, but the last three letters are too neat. I sign documents all day long. My handwriting runs together by the end.
Lorna tells me to send everything through her secure portal and not confront Grant until she’s reviewed it. She also tells me something that helps me think straight: a letter like this does not automatically place a lien on my house. Still, somebody may be using a false ownership statement to obtain credit, and we need to find out exactly what has been submitted.
I call my title company. A woman named Patrice checks the ownership record and confirms there’s no recorded mortgage or deed of trust against the property beyond what we already know. She recommends ordering an updated title search and alerting the county recorder about possible fraudulent filings.
I pay the fee and arrange both.
Then I sit at the breakfast counter, where a repairman is replacing a defective cabinet hinge, and look through the folder again. Beneath the letter is a photocopy of a business proposal for Walter’s old building-supply company.
He needs $310,000.
The business has lost two major customers. His warehouse rent is overdue, and a supplier has started demanding payment before delivering materials. Walter plans to refinance his operations, but the lender apparently wants stronger assurances.
Our home is listed under a heading marked Available Family Assets.
I have never seen that proposal before.
There is another sheet, this one showing expected household contributions. Grant has calculated how much money they’ll save if Walter, Denise, and Marcy live with us instead of maintaining separate residences. He’s included food, utilities, transportation, and even health insurance estimates.
In the monthly expense column, my contribution is listed as “primary.”
I am not a wife in that spreadsheet. I’m the funding source.
Lorna calls back after lunch. She says the documents raise serious questions about misrepresentation and an apparently forged signature, although the lender’s records will determine whether anything more formal has occurred. She advises me to preserve the originals and have no financial discussions without legal counsel.
I ask whether I should change the locks.
“Does Grant live there as his marital residence?”
“Yes.”
“Then don’t try to remove him yourself. We’ll handle the living arrangements legally.”
She suggests I contact the lender’s fraud department. We place the call together.
Brookfield confirms receipt of a preliminary application containing my name, but the representative will not disclose all the details without completing identity verification. I report that I never signed an ownership declaration or authorized my property to support Walter’s borrowing.
The representative provides a case number and says the disputed documents will be referred for review.
By the time Grant pulls into the driveway, I’ve made copies, contacted the appropriate people, and moved my personal financial records into the locking cabinet in my office.
I haven’t touched his belongings.
The moving truck comes first.
It’s enormous, with a yellow panel on the side, and the driver keeps looking at the narrow curve in our driveway. Grant parks behind it, followed by Walter and Denise in a rental SUV. Marcy steps out holding a paper cup of coffee and a little white dog.
Denise comes toward me smiling.
“Oh, Miriam, this is going to be wonderful.”
“Before anyone unloads,” I say, “we need to talk.”
Grant looks at the open front door and then at my face.
“Can this wait?”
“No.”
I hold up the copy of the Brookfield letter.
Walter’s smile disappears immediately.
Grant reaches for it, but I keep it in my hand.
“Did you sign this?”
He glances toward his father.
That glance tells me they both know what it is.
“That’s just preliminary paperwork,” Grant says.
“Did you sign it?”
“Yes. But nobody was going to take the house.”
“You represented yourself as authorized to offer my property as financial backing.”
“It’s our home.”
“And somebody signed my name.”
Marcy turns toward him. “What?”
Grant begins talking about how families help each other, how his father’s company employs eight people, and how I’m making a technical issue into a personal insult.
Walter finally admits that Grant drafted the paperwork. He says he believed Grant had discussed everything with me.
Grant doesn’t deny it.
I ask who signed my name.
Nobody answers.
Then Denise speaks quietly.
“Grant said you wouldn’t mind once the arrangements were finished.”
That hurts more than I expect. She knew I wasn’t being consulted and still packed her belongings.
I tell them the lender has been notified and the ownership declaration disputed. No one has permission to unload the truck. Grant can stay in the house while we arrange our separation properly, but his family cannot establish residence there.
Marcy starts crying. Not loudly. She puts her coffee on the roof of the SUV and says she never knew anything about the loan. She thought Grant had offered the rooms after talking with me.
I believe her.
Walter doesn’t argue. He takes out his phone and calls the moving company about storage. Denise sits in the passenger seat staring at her hands.
Grant follows me inside.
“You’re really going to do this over paperwork?”
I turn around.
“You signed something about my house without my permission. You let somebody sign my name. And you planned to make me responsible for your family’s expenses without asking me.”
He looks away when I mention the signature.
After a long silence, he admits that he copied my signature from an old insurance form onto the declaration. He says he expected to explain it before any loan was finalized.
I tell him an explanation afterward isn’t permission beforehand.
Over the following weeks, Lorna helps me document his admission and proceed with a separation. The lender confirms in writing that the disputed application has been withdrawn and that it has no security interest in my property. The updated title search shows no unexpected encumbrances. Lorna continues handling the false-document issue.
Grant moves into a rented apartment. His parents find temporary accommodation near Walter’s warehouse, and Marcy takes the apartment I’d offered to help her locate months earlier.
Our marriage doesn’t survive.
I’m still sorting out the divorce arrangements when my mother visits one Sunday. She sits downstairs in the room I reserved for her and complains that the bedside lamp is too bright.
I find a softer bulb in the utility drawer.
“Is that better?” I ask.
She turns the switch twice.
“Much. Now, did you remember to buy coffee?”
I tell her I did, and go put the kettle on.