2. The Birthday Dinner I Never Attended Exposed Years of Deception
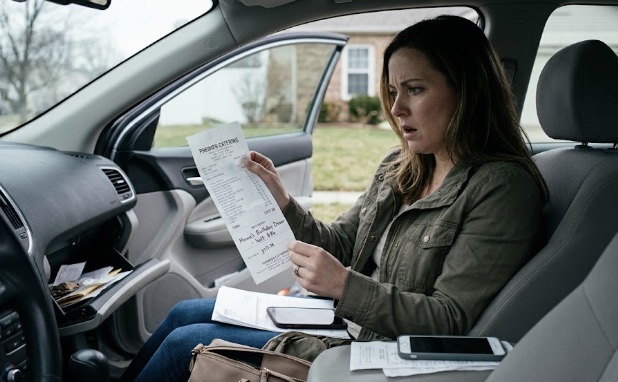
The receipt is wedged beneath the passenger seat, folded around a peppermint wrapper and a parking ticket. I only find it because I’m looking for the reading glasses my husband borrowed three days ago. At the top, in thick black print, are the words Cedar Grove Catering. Underneath is the final amount for his mother’s birthday dinner: $2,640. I recognize the date immediately. It’s the same Saturday I spent alone at home, eating tomato soup from a chipped Campbell’s mug while my husband celebrated with twenty-four members of his family. I wasn’t invited because, according to him, his mother wanted something small.
My husband, Grant, works as a regional sales director for a medical equipment company. I work at the public library, organizing children’s programs and helping older residents use computers. Grant makes nearly five times my salary, but we’ve divided every household expense equally since our wedding. He calls it financial independence. I call it having twelve dollars left until payday while a man with a six-figure income complains that I’ve bought the wrong brand of paper towels.
Two mornings after his mother’s birthday, he sends me a payment request for $86. His explanation is that we’re married, so family celebrations count as shared responsibilities, whether I attend or not. I remind him that I baked his mother a lemon cake and delivered it to her house the previous afternoon. He says that was my choice. I pay the money because I’m tired of arguing, and because I still believe that somewhere beneath Grant’s endless calculations is the generous man I married.
But the catering receipt tells a different story. Someone has written PAID IN FULL — CORPORATE ACCOUNT across the bottom. There’s also a business name I recognize from Grant’s expense reports, because I once helped him print several during a printer outage. I photograph both sides of the receipt and put it back exactly where I found it. That evening, while Grant watches television, I open our shared household spreadsheet and search for the birthday dinner.
The charge isn’t listed as $86. It’s listed as $1,320, with my name beside half of it. And when I scroll farther down, I notice a little gray column on the right that I’ve never seen before. Its heading is only three letters. The entries beneath it go back nearly four years. I click the first one, and the attached document opens.
The document isn’t another household bill. It’s a reimbursement confirmation from Grant’s employer, showing that an expense he’d charged to our marriage was paid back to him personally. I recognize the restaurant, the date, and the amount. Then I notice something worse: an identical payment appears in our account records, marked as…
…a household contribution from me.
I sit there staring at the screen while Grant laughs at something on television in the next room.
The original charge is from a dinner at a restaurant called Bellamy’s. According to our spreadsheet, we attended it together and divided the $418 bill equally.
I remember that dinner.
I also remember Grant spending most of the evening talking business with three clients while I listened politely and tried not to spill red sauce on my blouse.
He’d told me afterward that bringing spouses to business dinners was normal.
Apparently, so was charging your wife for half of a meal that your employer had already paid for.
I start checking other entries.
There are hotel stays, restaurant bills, parking charges, and even a $780 equipment rental from a company event. Grant classifies them as personal or household expenses in our spreadsheet, then claims reimbursement through his employer.
I don’t know whether every reimbursement was legitimate under his company’s rules. But I know I’m being charged for expenses he isn’t ultimately paying.
My hands start shaking when I find an entry for a conference in Nashville.
Grant attended alone.
I’d stayed home because my library was short-staffed.
Yet the spreadsheet shows that I contributed $612 toward the hotel.
I remember transferring that money.
He told me the conference was an investment in his career, and that stronger earnings would eventually benefit both of us.
I wasn’t sure why my paycheck needed to fund his career advancement, but I wanted to be supportive.
The expense report attached to the spreadsheet shows his company later reimbursed the hotel charge.
The payment went to his personal account.
I close the laptop when I hear footsteps.
Grant appears in the doorway carrying a glass of ice water.
“Still doing library stuff?”
“Just looking at the budget.”
He smiles.
“Good. You should pay more attention to where your money goes.”
He goes upstairs without waiting for an answer.
I don’t sleep much.
By morning, I’ve downloaded the shared spreadsheet, saved the reimbursement attachments I can access, and gathered bank statements showing the payments I’ve made.
I don’t change anything.
I don’t confront him.
Instead, I take a personal day and visit our credit union on Willow Street.
A woman named Denise meets with me in a little office near the lobby. There’s a crooked calendar behind her desk and a bowl of wrapped butterscotch candies beside her keyboard.
I explain that I’m trying to understand which accounts belong to me and which are shared.
Denise helps me review the records I’m authorized to access.
What she finds frightens me more than the catering receipt.
For three years, I’ve been paying down a joint credit card Grant calls our emergency account.
Its balance is just over $17,000.
I’d assumed the charges were mostly household repairs, car maintenance, and insurance payments.
But several payments I’ve made toward that balance followed expenses Grant was later reimbursed for. Other charges genuinely belonged to our household, and I can’t yet tell how much of the balance is connected to his work.
Denise cannot investigate his private reimbursement account or decide which expenses legally belong to him.
She does help me obtain copies of our joint statements.
“Before you agree to anything else,” she says, “have someone independent review these.”
I leave with forty-three printed pages in a manila envelope.
Outside, my car won’t start on the first attempt.
I turn the key again, listening to the engine struggle, and begin crying so hard that I have to sit in the parking lot until my breathing settles.
It’s not just the money.
It’s remembering every time Grant complained that I wasn’t saving enough.
Every secondhand coat I bought.
Every birthday invitation I declined because dinner out wasn’t in my budget.
And all those lectures about responsibility.
A week later, I meet with a divorce attorney named Elaine Foster.
She doesn’t promise me a fortune or tell me that everything Grant did is automatically illegal.
She explains that the bank records, reimbursement documents, marital debts, and financial disclosures all need to be examined carefully.
“Do not assume his income becomes yours,” she tells me. “But don’t assume a number in his spreadsheet determines your legal responsibility, either.”
We begin documenting the transactions.
By the time I tell Grant I want a separation, I’ve identified more than $14,000 in expenses for which I contributed money and for which the available records show reimbursements to him.
I expect anger.
Instead, Grant laughs.
“You’re divorcing me over bookkeeping?”
“No,” I say. “I’m divorcing you because you knew I was struggling, and you kept charging me anyway.”
His expression changes.
“We agreed to split expenses.”
“We agreed to share household expenses. We didn’t agree that I’d subsidize your business travel while you collected the reimbursements.”
“You’re twisting things.”
I slide copies of three expense reports across the kitchen table.
He looks at the first one.
Then the second.
On the third, his thumb starts rubbing the paper’s corner.
“Where did you get these?”
“From the folder attached to our shared budget.”
He stops talking.
For the first time since I’ve known him, Grant has nothing prepared to say.
The separation is unpleasant.
His attorney disputes several transactions. Mine requests additional records. We spend months sorting out which expenses were legitimate marital costs and which were reimbursed business charges.
Not every dollar I flagged is recoverable. Some records are incomplete, and several disputed charges were things we both used.
Eventually, we reach a written settlement.
Grant agrees to take responsibility for the remaining joint credit-card balance as part of our division of debts, subject to paying it off and closing the account. He also pays me $9,800 to settle the documented reimbursement dispute.
It’s less than the total I’d originally calculated.
But there’s another part of the agreement I care about just as much.
He must provide proof that the joint card is paid in full.
I won’t be signing anything that relies solely on his word.
On the afternoon our divorce is finalized, I stop at the grocery store on my way back to my rented apartment.
I buy fresh peaches, a package of chicken thighs, and the expensive coffee I’ve been passing over for years.
At checkout, I reach for my debit card.
My phone buzzes.
Grant has sent me a message.
You still owe me half the internet bill from last month.
I look at it while the cashier waits.
Then I forward it to Elaine, because our settlement already addresses that period’s household bills.
“Everything okay, ma’am?” the cashier asks.
“Yes,” I tell her, putting my phone away. “And could you add that little bunch of flowers by the register?”
She rings them up.
They’re $6.49.
I pay for them myself.